TSP Withdrawal Timeline: Step-by-Step Planning Guide
A TSP withdrawal isn't instant. From your actual last day of federal service, the practical timeline can run from one month to three months, because your agency must report your separation before TSP can process a post-separation withdrawal.
You retire in June, turn in your badge, and plan to use your TSP for July expenses. You submit what you believe is the right paperwork, then wait. July arrives without funds. The problem may not be your request at all. Your agency's payroll system may not yet have transmitted your separation data to TSP.
That handoff is the part many employees miss. TSP can process an eligible, properly completed request on a business-day schedule, but it can't begin the post-separation process until the government confirms that you separated. Your TSP withdrawal timeline is therefore a relay race involving your agency, its payroll or personnel system, TSP, and your bank.
Why Your TSP Withdrawal Timeline Feels Slower Than Expected
Consider a common retirement scenario. A federal employee retires on the final day of June and expects a TSP payment in July. The employee has already chosen a distribution method, verified the mailing address, and assumes the request clock begins on the retirement date.
It doesn't necessarily. TSP must receive the separation information from the employing agency or uniformed service before the employee can use the post-separation withdrawal process. TSP's own withdrawal guidance makes employment status the first checkpoint. An employee who hasn't separated can't use the post-separation process, even while in nonpay status.
The date that matters may not be your last day
Your separation date is the day your federal employment ends. Your reporting date is when your agency transmits that separation to TSP. Your processing date is when TSP can act on an eligible, completed request. Those are separate events, and treating them as one creates unrealistic cash-flow assumptions.
Independent reporting notes that distributions may be delayed by up to 30 days after retirement while a payroll provider notifies TSP of the separation. That possibility is separate from TSP's own processing schedule, which means a same-day internal processing rule doesn't guarantee same-day eligibility or money in your bank account.
Practical rule: Build your spending plan around the reporting handoff, not the date printed on your retirement paperwork.
Employment status also changes the rules. Federal employees may make an age-based in-service withdrawal beginning at age 59½, provided the account balance is vested. The minimum request is generally $1,000, unless the participant's entire vested balance is lower, and participants may make up to four age-59½ in-service withdrawals during a calendar year. Since May 15, 2024, participants no longer have to wait 30 calendar days between age-based in-service withdrawal requests, according to TSP's explanation of in-service withdrawal types.
For a separated employee, eligibility generally requires at least 31 days without federal reemployment, unless the participant doesn't expect to be rehired after a break of fewer than 31 days. That rule sits between the separation report and the withdrawal request, so it belongs in your planning calendar.
Delays usually have identifiable causes
When clients tell me their TSP withdrawal is “stuck,” I first look for a handoff problem, not a TSP processing problem. The usual trouble spots are straightforward:
- Separation data hasn't arrived: TSP can't treat you as separated until the agency or service reports the separation.
- The request was submitted too early: A completed form won't overcome an unreported separation.
- A loan remains unresolved: An outstanding loan can complicate the exit and requires prompt attention after the separation report.
- Bank information is incomplete: A payment election can't work smoothly if direct-deposit details need correction.
- Calendar days replace business days: TSP's processing schedule doesn't mean weekends and holidays count as processing days.
Once you identify which handoff is incomplete, you can call the right office, ask a precise question, and build a realistic reserve for rent, healthcare premiums, taxes, and other essential expenses.
Mapping the Key Milestones in Your TSP Withdrawal Timeline
The cleanest way to manage this process is to separate the retirement date from the administrative milestones that follow. Use the sequence below instead of relying on one optimistic payment date.
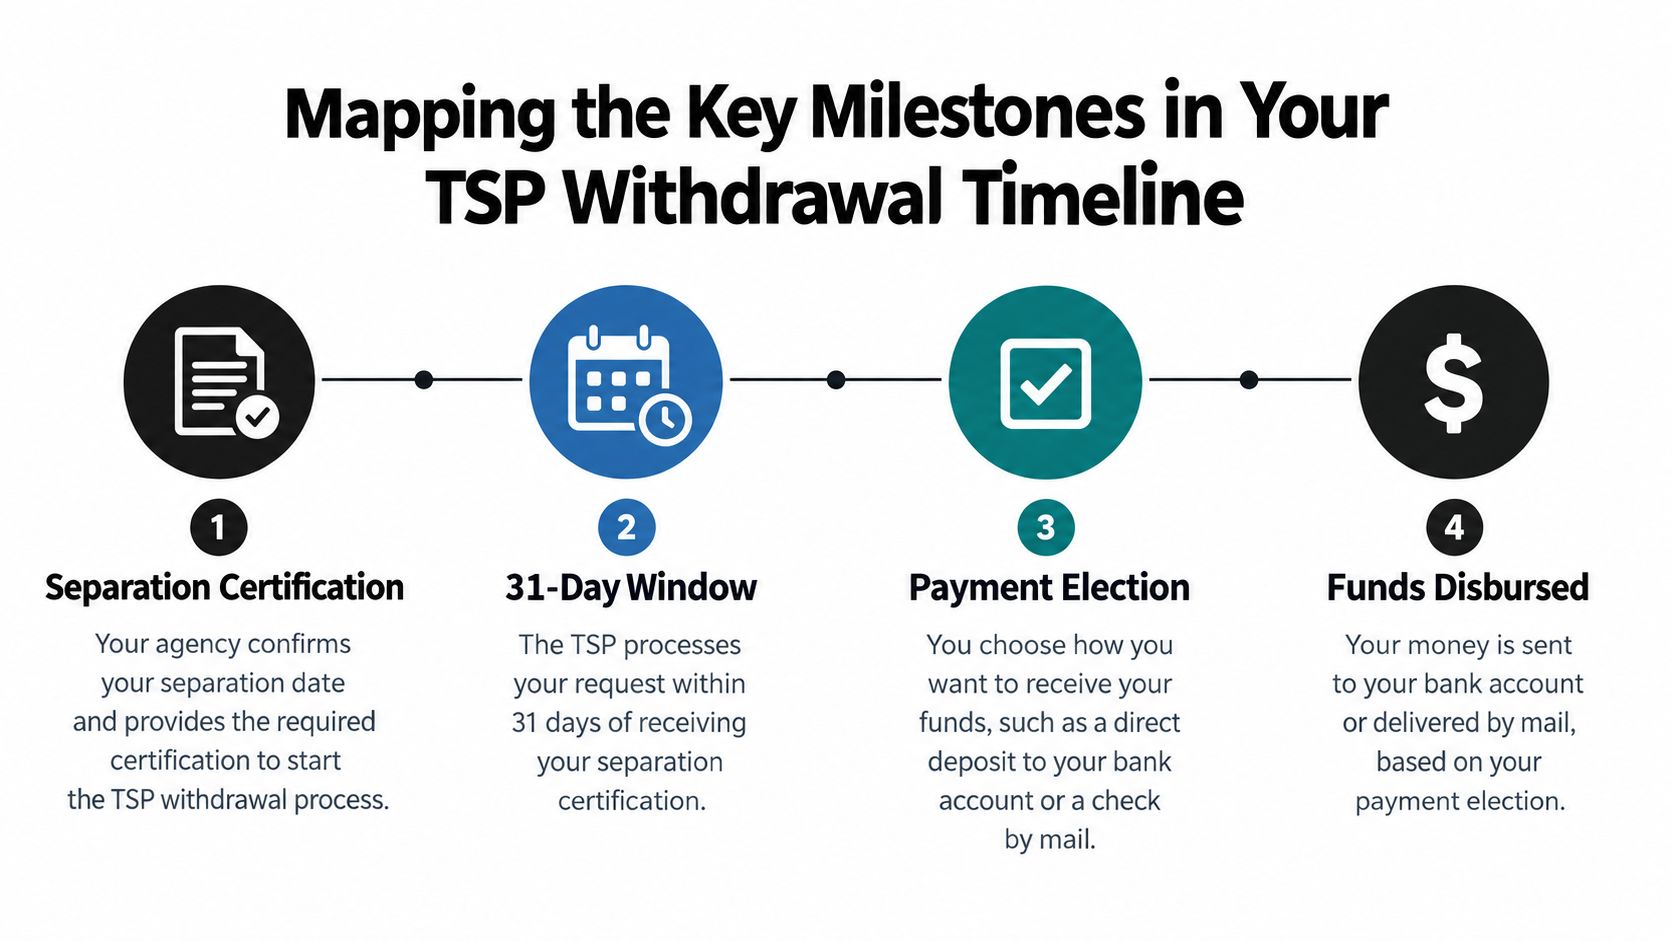
Milestone one is separation certification
Your agency must report your separation date to TSP. Ask human resources or payroll when that transmission occurs, and then verify the status with TSP rather than assuming the agency's internal completion means TSP has received the information.
This distinction matters because the retirement date starts your personal transition, but the agency report determines whether TSP can recognize you as eligible for the post-separation workflow. If the report hasn't arrived, submitting a withdrawal request may only create another incomplete step.
Milestone two is the eligibility window
After separation, eligibility generally requires 31 days without federal reemployment, subject to the exception for someone not expecting to be rehired after a break of fewer than 31 days. Don't treat this as a casual waiting period. It's a formal checkpoint that affects when TSP can accept the post-separation request.
An unresolved TSP loan also belongs on this calendar. For a separated federal employee, the practical guidance is to close or repay an outstanding loan within 90 days of the separation report, as described in OPM's retirement payment guidance. Leaving the loan unresolved can create avoidable friction exactly when you need a clean account transition.
Milestone three is request submission
Once your separation is reported and your eligibility is established, verify your bank information and submit the request through TSP's online withdrawal workflow. Select the distribution type carefully. You may choose a partial distribution, total distribution, annuity purchase, or installments.
TSP processes requests every business day. Requests entered before noon Eastern Time are generally processed that night, while later requests move to the next business processing night. OPM states that a properly completed request generally takes 7 to 10 business days to process, with additional time potentially required for payment delivery.
You can monitor the request in My Account or through the ThriftLine. That tracking step is useful because it replaces guesswork with a visible status and gives you a better basis for contacting TSP.
Milestone four is payment issuance
Payment issuance is not identical to request processing. A request can finish its internal review before your bank receives the funds. For separated participants receiving installments, TSP issues later payments on the 15th of the month, or the next business day when the 15th isn't a business day. Participants should still allow several days for payment processing.
Use this sequence to diagnose your position:
- Separation date: Your federal employment ends.
- Agency certification: Your agency reports the separation to TSP.
- Eligibility window: The applicable post-separation requirements are satisfied.
- Payment election: You submit a complete request and select the distribution method.
- TSP processing: TSP reviews and processes the request on its business-day schedule.
- Funds disbursed: TSP issues payment, and your bank or mail delivery completes the final leg.
This video provides another visual explanation of the withdrawal process and the decisions that can affect your transition.
The important planning insight is simple. The clock has multiple starts. Your last day starts retirement, the agency report starts TSP's eligibility review, and your completed request starts TSP's processing window.
Choosing Your Distribution Type and How It Shapes the TSP Withdrawal Timeline
Your distribution choice affects more than the amount you receive. It determines whether you're asking TSP for one payment, a recurring schedule, an annuity purchase, or a partial transfer. The administrative path and tax treatment differ, so make the decision before you need the cash.
A partial or total distribution is usually the most direct choice when you have a defined cash need. An installment election is better suited to planned income replacement, but it introduces a recurring payment schedule that you must monitor. An annuity purchase can require more coordination because you're converting the account balance into an income arrangement rather than requesting a simple payment.
| Distribution Type | Processing Speed | Tax Handling | Flexibility |
|---|---|---|---|
| Partial distribution | Follows TSP's completed-request processing schedule | Tax treatment depends on the account source and election | Provides a defined amount while leaving the rest invested |
| Total distribution | Follows the same eligibility and request requirements | May create a substantial taxable event for traditional funds | Simplifies the account but removes future TSP balance |
| Installments | Initial request follows the processing schedule; later payments follow the selected schedule | Taxes apply according to the taxable portion of each payment | Creates recurring income with monthly, quarterly, or annual options |
| Annuity purchase | Requires an election and annuity processing rather than a simple cash payment | Tax treatment depends on the annuity and account components | Converts assets into an income stream with less withdrawal flexibility |
A partial distribution must generally be at least $1,000, according to TSP's in-service withdrawal terms. Installments can be scheduled monthly, quarterly, or annually. Those choices should reflect your spending plan, not just which option appears fastest on the screen.
Match the method to the need
If you need funds for a specific transition expense, a partial distribution may preserve more control than a total distribution. If you need predictable income, installments may fit better, but you'll need enough outside liquidity to cover the gap before the first payment arrives.
An annuity deserves separate analysis. It may provide a structured income stream, but it generally offers less flexibility after purchase. Review the trade-offs in this guide to whether a TSP annuity fits federal retirement planning before selecting it under time pressure.
Tax timing is also part of the distribution decision. Most withdrawals before age 59½ can incur the IRS early-withdrawal penalty, but the penalty generally doesn't apply when an employee separates during or after the year they reach age 55, as explained in TSP's retirement withdrawal guidance. Don't confuse avoiding the early-withdrawal penalty with avoiding income tax. Those are different questions.
Decision rule: Choose the distribution type based on the income job the money must perform, then confirm the tax result before submitting the election.
The Rollover vs. Taxable Distribution Decision
A TSP exit creates two separate decisions. First, determine when and how the money can leave the account. Then decide whether it should move to another retirement account or become cash in your hands.
A direct rollover to an eligible IRA or retirement plan generally preserves tax deferral and avoids treating the transferred amount as current cash income. A taxable distribution gives you immediate access, but it can create income tax consequences and may trigger withholding. Your choice should reflect your spending need, tax position, investment preferences, and tolerance for managing the money outside TSP.
Direct rollover is usually cleaner for retirement money
If you don't need the funds for current spending, a direct rollover is usually the cleaner administrative path. The money moves from TSP to the receiving retirement account without passing through your personal bank account, helping preserve the tax-deferred structure.
A rollover still requires careful coordination. Confirm that the receiving institution accepts the intended TSP funds, that the account registration matches, and that the destination instructions are correct. The complete guide to rolling over a TSP to an IRA can help you identify the decisions before you submit the request.
A taxable distribution may make sense when you need the money for living expenses or a clearly defined obligation. It can also be appropriate when your overall retirement plan intentionally uses withdrawals during a lower-income period. But don't select “cash” just because it appears easier. The tax result can be more expensive than the administrative convenience.
Avoid taking possession without a plan
When you receive retirement funds personally and intend to redeposit them, timing rules become your responsibility. Missing the applicable redeposit deadline can turn a planned rollover into a taxable distribution. A direct rollover avoids placing the money in your hands in the first place.
Tax withholding also deserves attention. The research material for this topic identifies 20% withholding as a risk for certain lump-sum distributions. That withholding is not necessarily the final tax bill, and it doesn't eliminate the need to plan for any remaining tax due.
Your age and separation year matter as well. A withdrawal can avoid the early-withdrawal penalty under the applicable separation rule while still producing taxable income. Before choosing cash, ask three questions:
- Will I need this money for current expenses?
- Can I absorb the taxable income in the year of distribution?
- Am I giving up an important retirement-account feature by taking cash?
If the answers aren't clear, pause the request and consult a tax professional or federal benefits advisor before turning a timing problem into a tax problem.
Actionable Steps to Optimize Your TSP Withdrawal Timeline
The fastest process is usually the one you prepare before your final day. You can't control every payroll handoff, but you can eliminate the errors that force TSP to request more information or delay payment.
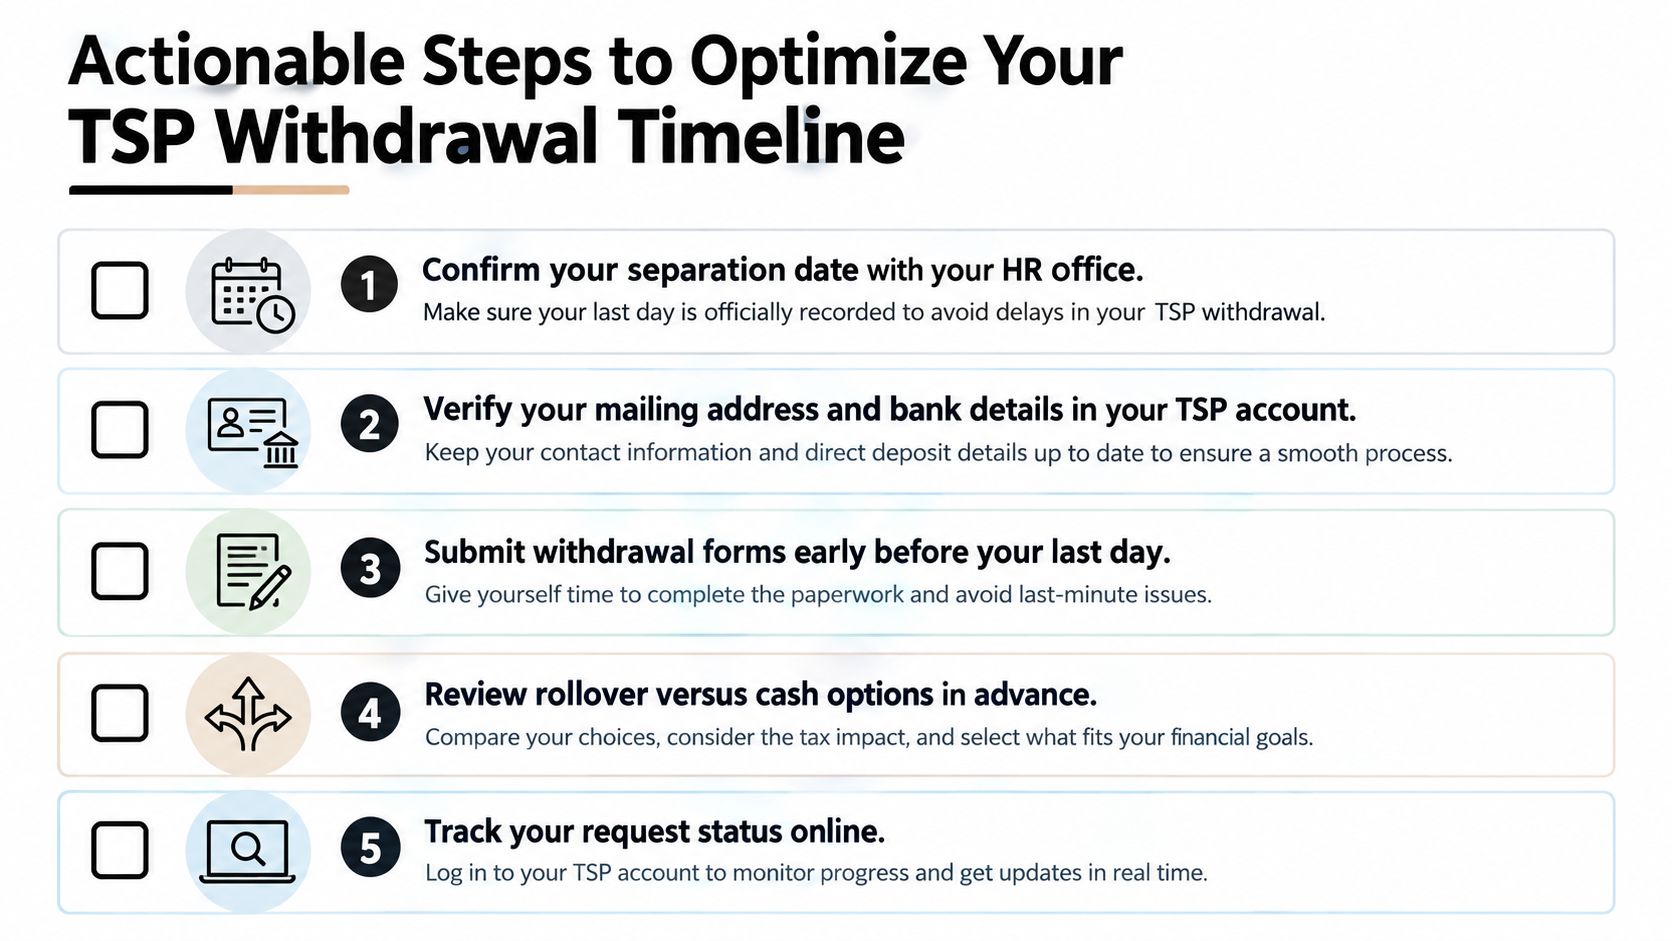
Prepare the account before separation
Start with the details TSP and your agency will need:
- Confirm the separation date: Ask HR or payroll when the separation will be reported to TSP, not merely when your retirement paperwork is approved.
- Verify direct deposit: Add or update bank information at least seven days before requesting a withdrawal, following OPM's guidance on retirement payment administration.
- Review the loan balance: Decide how you'll close or repay any TSP loan after the separation report, and keep evidence of the transaction.
- Choose the distribution method: Decide whether you need cash, a partial payment, installments, an annuity purchase, or a direct rollover.
- Build a cash reserve: Keep essential expenses outside the TSP while the agency, TSP, and bank complete their separate steps.
Don't wait until your last day to discover that your bank account is closed, your address is outdated, or your chosen rollover institution needs different instructions. These are small corrections when handled early and expensive distractions when handled during retirement.
Track the handoff actively
After separation, contact HR or payroll to confirm that the separation report was sent. Then check My Account or contact the ThriftLine to verify that TSP recognizes the separation. If the status hasn't changed, ask the agency which office owns the transmission rather than repeatedly resubmitting the withdrawal request.
Federal Benefits Sherpa offers personalized benefit reviews, retirement planning, gap analysis reports, and educational resources for federal employees evaluating TSP, healthcare, and Social Security decisions. If you're coordinating content or education for a financial practice, a resource on digital strategy for financial firms can also help explain complex planning topics clearly to clients.
For tax coordination, review this guide to TSP and taxes for federal employees before selecting a taxable distribution. Your withdrawal request should fit the broader retirement-income plan, not operate as an isolated transaction.
What I tell clients: Call before the delay becomes urgent. The earlier you identify the missing handoff, the more choices you retain.
Conclusion and Taking Control of Your Retirement Transition
A reliable TSP withdrawal timeline has a clear order. Your agency confirms the separation, the applicable eligibility period is satisfied, you resolve any loan issue, you verify banking information, and then you submit a complete request. TSP's processing schedule begins only after the request is eligible and properly completed.
The most common mistake is planning from the final payment date backward without accounting for the agency-to-TSP handoff. Your last day of work, the agency's reporting date, TSP's processing date, and the bank's receipt date all belong on the calendar. If you need retirement funds for essential expenses, maintain a contingency reserve and don't schedule an unavoidable payment around the most optimistic estimate.
Your distribution election matters just as much as the timing. A partial payment may cover a defined need, installments may support recurring income, an annuity may create structured payments, and a direct rollover may preserve tax deferral. Each choice creates different consequences, so make the decision before the request screen is open and the pressure is high.
The practical approach is disciplined rather than complicated:
- Confirm who reports your separation and when.
- Verify that TSP recognizes the separation.
- Resolve any outstanding loan within the applicable period.
- Confirm direct-deposit details in advance.
- Choose the tax and distribution path deliberately.
- Track the request until payment is issued.
That preparation won't make every government handoff instant. It will prevent the avoidable errors that turn a manageable retirement transition into a cash-flow crisis. Federal retirement is already a major change. Your TSP should support that transition, not dictate it because an administrative milestone was overlooked.
Federal Benefits Sherpa helps federal employees evaluate retirement benefits, TSP decisions, healthcare coverage, Social Security, and income gaps through personalized planning and benefit reviews. Visit Federal Benefits Sherpa to schedule a review and build a withdrawal plan around your actual separation date, cash needs, and tax choices.
